Blogs, insights, guides and videos on India's unlisted market — all in one place.
<p>API Holdings, PharmEasy ki parent company, ne Thyrocare ka 10% stake bech kar ₹667 crore raise kiye hain!</p>
<p>HDFC Securities ka Q2FY26 profit 36% gir kar ₹200 crore par aa gaya hai! Revenue, interest income aur commission — sabhi fronts par decline dikh raha hai.</p>
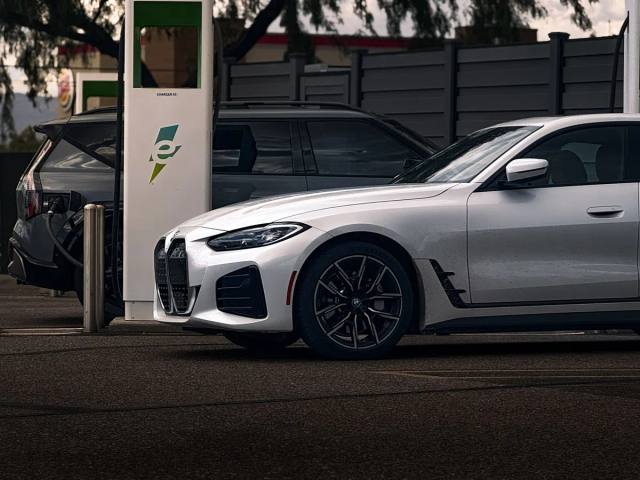
<p>Goa Shipyard Limited has delivered its best-ever performance in FY25 — achieving record revenue, a robust ₹16,000 crore order book, and major strides in localisation under the Make in India and Aatmanirbhar Bharat initiatives. From advanced frigates and patrol vessels to 100% indigenous floating docks, GSL is redefining India’s naval shipbuilding strength. Despite short-term margin pressure due to high-value project execution, the company’s strong financial position, modernised infrastructure, and global export wins signal a powerful course for long-term growth.</p>
<h2 data-pm-slice="1 1 []">boAt’s Parent Imagine Marketing Gets SEBI Nod for ₹1,500-Crore IPO</h2> <p><strong>Imagine Marketing Limited</strong>, the parent company of India’s leading wearables brand <strong>boAt</strong>, has received approval from the <strong>Securities and Exchange Board of India (SEBI)</strong> to launch its long-awaited <strong>₹1,500-crore initial public offering (IPO)</strong>.</p> <h3>A) IPO Structure and Key Details</h3> <p>According to the updated draft red herring prospectus (DRHP) filed on <strong>October 29</strong>, the IPO will consist of:</p> <ul data-spread="false"> <li> <p><strong>Fresh issue:</strong> ₹500 crore</p> </li> <li> <p><strong>Offer for Sale (OFS):</strong> ₹1,000 crore by existing investors</p> </li> </ul> <p>The OFS will include:</p> <ul data-spread="false"> <li> <p>₹75 crore by <strong>Sameer Ashok Mehta</strong></p> </li> <li> <p>₹225 crore by <strong>Aman Gupta</strong></p> </li> <li> <p>₹500 crore by <strong>South Lake Investment Limited</strong> (Promoter Selling Shareholder)</p> </li> <li> <p>₹150 crore by <strong>Fireside Ventures Investment Fund-I</strong></p> </li> <li> <p>₹50 crore by <strong>Qualcomm Ventures LLC</strong></p> </li> </ul> <h3>B) Utilization of IPO Proceeds</h3> <p>The company plans to utilize the <strong>fresh issue proceeds</strong> for:</p> <ul data-spread="false"> <li> <p><strong>₹225 crore</strong> – Funding working capital requirements</p> </li> <li> <p><strong>₹150 crore</strong> – Brand and marketing expenses to enhance product visibility</p> </li> <li> <p>Remaining amount – General corporate purposes</p> </li> </ul> <h3>C) A Second Attempt at Public Listing</h3> <p>This marks <strong>boAt’s second IPO attempt</strong>. The company had earlier filed for a <strong>₹2,000-crore IPO in January 2022</strong>, which included a fresh issue of ₹900 crore and an OFS of ₹1,100 crore. However, it deferred the plan due to volatile market conditions and opted for the confidential pre-filing route in <strong>April 2025</strong>, gaining SEBI’s approval by <strong>August</strong>.</p> <p>The confidential filing mechanism allowed the company to submit draft documents privately and make public disclosures only at a later stage — a flexible route increasingly preferred by large startups.</p> <h3>D) Struggling Financials of Boat.</h3> <p>After posting <strong>two consecutive years of losses</strong>, boAt barely returned to profitability in FY25, with a <strong>net profit of just ₹61 crore</strong> — a modest recovery from a <strong>loss of ₹53 crore in FY24</strong> and <strong>₹129 crore in FY23</strong>.</p> <p>However, a closer look reveals <strong>stagnation at the topline</strong>.<br />Revenue has been largely <strong>flat for three years</strong>, inching down from ₹3,377 crore in FY23 to ₹3,073 crore in FY25 — indicating a slowdown in growth momentum.</p> <p>Within its segments, the performance gap is striking:</p> <ul data-spread="false"> <li> <p>The <strong>audio accessories</strong> division, still the company’s mainstay, managed only a <strong>10% revenue growth</strong> — from ₹2,351 crore in FY23 to ₹2,586 crore in FY25.</p> </li> <li> <p>The <strong>wearables business</strong>, once a key growth driver, <strong>collapsed by nearly 58%</strong>, with sales plunging from ₹783 crore in FY23 to just ₹330 crore in FY25.</p> </li> </ul> <p>While boAt has made attempts to diversify into <strong>personal grooming and mobile accessories</strong>, these categories are yet to contribute meaningfully to overall revenues.</p> <p>In short, the company’s financials depict a <strong>stagnant topline, falling market share, and shrinking growth opportunities</strong> — raising serious questions about the sustainability of its current valuation.</p> <h3>E) Company Overview</h3> <p>Founded in <strong>2013</strong> by <strong>Aman Gupta</strong> and <strong>Sameer Mehta</strong>, <strong>Imagine Marketing Ltd</strong> has built <strong>boAt</strong> into one of India’s most recognizable lifestyle electronics brands. Its portfolio spans:</p> <ul data-spread="false"> <li> <p><strong>Audio gear:</strong> Earphones, headphones, speakers</p> </li> <li> <p><strong>Smart wearables:</strong> Smartwatches and fitness trackers</p> </li> <li> <p><strong>Personal grooming products</strong></p> </li> <li> <p><strong>Mobile accessories</strong></p> </li> </ul> <p>The company has effectively combined <strong>youth-focused branding</strong>, <strong>competitive pricing</strong>, and <strong>digital marketing</strong> to maintain a leading position in India’s consumer electronics space.</p> <h3>F) Lead Managers</h3> <p>The IPO will be managed by:</p> <ul data-spread="false"> <li> <p><strong>ICICI Securities</strong></p> </li> <li> <p><strong>Goldman Sachs (India) Securities</strong></p> </li> <li> <p><strong>JM Financial</strong></p> </li> <li> <p><strong>Nomura Financial Advisory and Securities (India) Pvt Ltd</strong></p> </li> </ul> <h2> Conclusion</h2> <h3><em>Our View on boAt’s Upcoming ₹1,500 Cr IPO</em></h3> <p>boAt is planning a ₹1,500 crore IPO — comprising ₹1,000 crore of Offer for Sale (OFS) and ₹500 crore of fresh issue.<br />Promoters will partially exit through the OFS route.</p> <p>However, when we look at fundamentals, the picture isn’t exciting. Over the last three years, <strong>boAt’s topline has shown almost no growth</strong>, and its key category — <strong>wearables — has been consistently losing market share</strong>.<br />In audio too, competition from <strong>Noise, Fire-Boltt, and other aggressive brands</strong> has intensified, eroding boAt’s earlier dominance.</p> <p>At its core, boAt has always been a <strong>trading business</strong> — importing products from China and selling them via Amazon and Flipkart. There’s <strong>no strong brand moat or proprietary technology</strong> to protect margins.</p> <p>The last fundraise valued the company at <strong>₹10,000 crore</strong>, but with FY25 PAT around ₹60 crore, that implies a <strong>P/E of ~166x</strong>, which is steep for a business showing <em>zero growth and rising competition.</em></p> <p>In our view, the <strong>fair valuation lies closer to ₹3,000–4,000 crore</strong>, unless the company demonstrates a clear turnaround in growth, profitability, and product differentiation.</p> <h3>Disclaimer</h3> <p>UnlistedZone is not a SEBI-registered Research Analyst or Investment Advisor. All information provided on our platform is strictly for educational and informational purposes. We do not offer investment advice or stock recommendations. Investors are advised to conduct their own due diligence or consult a SEBI-registered advisor. Investments in unlisted and pre-IPO shares are subject to market risks including illiquidity and volatility. UnlistedZone does not assure any returns or accept liability for investment outcomes based on this report.</p>
<h1 data-source-line="5-5"><strong>Sunday Proptech (OYO Assets): A Deep Dive into India's Emerging Hospitality Investment Platform</strong></h1> <p data-source-line="7-7"><em>Understanding the Asset Ownership Strategy Behind OYO's Latest Venture</em></p> <hr data-source-line="9-9" /> <h2 data-source-line="11-11"><strong>1. What is Sunday Proptech?</strong></h2> <p data-source-line="13-13"><strong>Sunday Proptech Limited</strong>, operating as <strong>OYO Assets</strong>, represents a strategic pivot in the hospitality investment landscape. Launched in September 2025, it is positioned as India's most ambitious hotel ownership and asset management platform, designed to acquire, upgrade, and operate high-potential hotel properties both in India and globally.</p> <p data-source-line="15-15">Unlike traditional OYO operations which follow an <strong>asset-light model</strong> (providing technology and management services without owning properties), Sunday Proptech is an <strong>asset-heavy ownership platform</strong>. The company acquires undervalued or high-growth potential hotels, upgrades them to premium mid-stay brands (like Sunday Hotels and Studio 6/Motel 6), and generates sustainable cash flows through ownership.</p> <h3 id="key-characteristics%3A" tabindex="-1" data-source-line="17-17"><strong>a) Key Characteristics:</strong></h3> <ul data-source-line="19-25"> <li data-source-line="19-19"><strong>Current Portfolio:</strong> 8 operational hotels (primarily in the USA)<br /><br /></li> <li data-source-line="20-20"><strong>Expansion Pipeline:</strong> 8 additional properties under acquisition<br /><br /></li> <li data-source-line="21-21"><strong>Geographic Presence:</strong> United States and India<br /><br /></li> <li data-source-line="22-22"><strong>Brand Portfolio:</strong> Sunday Hotels (India), Studio 6/Motel 6 (USA)<br /><br /></li> <li data-source-line="23-23"><strong>Revenue Model:</strong> Direct hotel ownership generating rental income and operational profits<br /><br /></li> <li data-source-line="24-25"><strong>Competitive Edge:</strong> Market-leading RevPAR (Revenue Per Available Room) driven by OYO's distribution network and technology stack</li> </ul> <h3 id="the-properties%3A" tabindex="-1" data-source-line="26-26"><strong>b) The Properties:</strong></h3> <p data-source-line="28-28"><strong>US Portfolio (8 Hotels - 691 Keys Total):</strong></p> <ul data-source-line="29-37"> <li data-source-line="29-29">Greenville Haywood Mall (72 keys, ₹11.6 Cr annual revenue)<br /><br /></li> <li data-source-line="30-30">Cincinnati Fairfield (72 keys, ₹11.6 Cr revenue)<br /><br /></li> <li data-source-line="31-31">Shreveport Bossier City (124 keys, ₹13.3 Cr revenue)<br /><br /></li> <li data-source-line="32-32">St. Louis Westport Craig Road (71 keys, ₹9.1 Cr revenue)<br /><br /></li> <li data-source-line="33-33">Charlotte Tyvola Road (72 keys, ₹11.6 Cr revenue)<br /><br /></li> <li data-source-line="34-34">Cincinnati Florence Meijer Dr. (72 keys, ₹8.3 Cr revenue)<br /><br /></li> <li data-source-line="35-35">Indianapolis North Carmel (72 keys, ₹10 Cr revenue)<br /><br /></li> <li data-source-line="36-37">Huntsville US Space & Rocket Center (108 keys, ₹15.8 Cr revenue)</li> </ul> <p data-source-line="38-38"><strong>c) Average EBITDA margins across US properties: 38-46%</strong></p> <p data-source-line="40-40"><strong>d) India Portfolio (4 Hotels - 418 Keys):</strong></p> <ul data-source-line="41-45"> <li data-source-line="41-41">Sunday Hotel Ahmedabad (66 keys, ₹5.3 Cr annual revenue)<br /><br /></li> <li data-source-line="42-42">Sunday Hotel Vadodara (96 keys, ₹7.4 Cr revenue)<br /><br /></li> <li data-source-line="43-43">Sunday Hotel Jaipur (90 keys, ₹13.8 Cr revenue)<br /><br /></li> <li data-source-line="44-45">Sunday Hotel Chandigarh Zirakpur (166 keys, ₹16.6 Cr revenue)</li> </ul> <hr data-source-line="46-46" /> <h2 data-source-line="48-48"><strong>2. Who Are the Shareholders in Sunday Proptech?</strong></h2> <p data-source-line="50-50">Sunday Proptech operates as a <strong>Joint Venture (JV)</strong> structure with a carefully curated shareholder base that brings both strategic and financial strength:</p> <h3 id="primary-shareholders%3A" tabindex="-1" data-source-line="52-52"><strong>a) Primary Shareholders:</strong></h3> <p data-source-line="54-54"><strong>1. Oravel Stays Limited (OYO)</strong> - The Parent Company</p> <ul data-source-line="55-59"> <li data-source-line="55-55">World's leading digital hotel company<br /><br /></li> <li data-source-line="56-56">Operates in 35+ countries<br /><br /></li> <li data-source-line="57-57">23,000+ hotels and 224,000+ vacation homes<br /><br /></li> <li data-source-line="58-59">FY25 metrics: ₹16250 Cr GBV, ₹6,253 Cr Revenue, ₹1036 Cr EBITDA</li> </ul> <p data-source-line="60-61"><strong>2. Key Existing OYO Shareholders</strong> The marquee investor base includes global institutional investors who have backed OYO's growth story.</p> <p data-source-line="63-63"><strong>3. InCred</strong> (May 2025 Private Placement)</p> <ul data-source-line="64-66"> <li data-source-line="64-64">Invested at ₹1 per share<br /><br /></li> <li data-source-line="65-66">Acquired 2 Crore equity shares</li> </ul> <p data-source-line="67-67"><strong>4. Tattva (Fund)</strong> (July 2025 Private Placement)</p> <ul data-source-line="68-71"> <li data-source-line="68-68">Invested at ₹52.5 per share<br /><br /></li> <li data-source-line="69-69">Acquired 62.86 Lakh equity shares<br /><br /></li> <li data-source-line="70-71">Represents significant valuation markup within 2 months</li> </ul> <h3 id="share-structure-timeline%3A" tabindex="-1" data-source-line="72-72"><strong>b) Share Structure Timeline:</strong></h3> <div class="table-container"> </div> <div class="table-container"><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761818511.jpg" alt="" width="643" height="450" /></div> <p data-source-line="82-82"><strong>Total Outstanding Shares (as of October 2025): 37.47 Crore shares (374,737,010)</strong></p> <p data-source-line="84-84">The structure is deliberately kept separate from OYO's core operations to maintain the distinction between the asset-light technology platform (OYO) and the asset-heavy ownership business (Sunday Proptech).</p> <hr data-source-line="86-86" /> <h2 data-source-line="88-88"><strong>3. Why is OYO Starting This Company?</strong></h2> <p data-source-line="90-90">The creation of Sunday Proptech represents a <strong>strategic evolution</strong> in OYO's business model, driven by multiple compelling rationales:</p> <h3 id="a.-replicating-global-best-practices" tabindex="-1" data-source-line="92-92"><strong>A. Replicating Global Best Practices</strong></h3> <p data-source-line="94-94">The world's leading hospitality brands have successfully deployed a <strong>dual-structure model</strong>:</p> <p data-source-line="96-96"><strong>Asset-Light Franchise/Brand Company + Asset-Heavy Ownership Platform</strong></p> <p data-source-line="98-98"><strong>Global Examples:</strong></p> <ul data-source-line="99-103"> <li data-source-line="99-99"><strong>Marriott International</strong> (Brand) → <strong>Ventive Hospitality</strong> (Asset Owner in India)<br /><br /></li> <li data-source-line="100-100"><strong>IHG Hotels & Resorts</strong> (Brand) → <strong>Samhi Hotels</strong> (Asset Owner in India)<br /><br /></li> <li data-source-line="101-101"><strong>Indian Hotels Company (IHCL/Taj)</strong> (Brand) → <strong>TajGVK</strong> (Asset Owner in South India)<br /><br /></li> <li data-source-line="102-103"><strong>Hilton Worldwide</strong> (Brand) → Multiple REITs and Ownership Platforms</li> </ul> <p data-source-line="104-104">This separation allows:</p> <ul data-source-line="105-108"> <li data-source-line="105-105">The brand company to scale globally without capital intensity<br /><br /></li> <li data-source-line="106-106">The asset company to capture real estate appreciation and operational yields<br /><br /></li> <li data-source-line="107-108">Shareholders to choose their risk-return profile (growth vs. income)</li> </ul> <h3 id="b.-unlocking-dual-value-streams" tabindex="-1" data-source-line="109-109"><strong>B. Unlocking Dual Value Streams</strong></h3> <p data-source-line="111-111"><strong>OYO's Core Business (Asset-Light):</strong></p> <ul data-source-line="112-115"> <li data-source-line="112-112">High scalability, low capital requirements<br /><br /></li> <li data-source-line="113-113">Technology and brand licensing fees<br /><br /></li> <li data-source-line="114-115">Network effects from demand aggregation</li> </ul> <p data-source-line="116-116"><strong>Sunday Proptech (Asset-Heavy):</strong></p> <ul data-source-line="117-121"> <li data-source-line="117-117">Real asset backing with tangible value<br /><br /></li> <li data-source-line="118-118">Predictable annuity income streams<br /><br /></li> <li data-source-line="119-119">Protection during market volatility<br /><br /></li> <li data-source-line="120-121">Upside from property appreciation</li> </ul> <h3 id="c.-competitive-advantages" tabindex="-1" data-source-line="122-122"><strong>C. Competitive Advantages</strong></h3> <p data-source-line="124-124">Sunday Proptech leverages OYO's decade-long operational expertise:</p> <ol data-source-line="126-131"> <li data-source-line="126-126"><strong>Distribution Strength:</strong> OYO's 132 million+ app downloads drive occupancy<br /><br /></li> <li data-source-line="127-127"><strong>Technology Stack:</strong> Revenue management, dynamic pricing, operational automation<br /><br /></li> <li data-source-line="128-128"><strong>Market-Leading RevPAR:</strong> Superior revenue per room vs. competitors<br /><br /></li> <li data-source-line="129-129"><strong>Lowest Cost Structure:</strong> Technology-driven operational efficiency<br /><br /></li> <li data-source-line="130-131"><strong>Brand Portfolio:</strong> Established brands (Sunday Hotels, Motel 6) accelerate turnaround</li> </ol> <h3 id="d.-capital-efficiency-strategy" tabindex="-1" data-source-line="132-132"><strong>D. Capital Efficiency Strategy</strong></h3> <p data-source-line="134-134">Rather than building hotels from scratch (greenfield development), Sunday Proptech:</p> <ul data-source-line="135-139"> <li data-source-line="135-135">Acquires undervalued or underperforming properties<br /><br /></li> <li data-source-line="136-136">Applies OYO's branding and technology for rapid turnaround<br /><br /></li> <li data-source-line="137-137">Generates cash flows faster than new construction<br /><br /></li> <li data-source-line="138-139">Captures yield and valuation arbitrage</li> </ul> <h3 id="e.-market-opportunity" tabindex="-1" data-source-line="140-140"><strong>E. Market Opportunity</strong></h3> <p data-source-line="142-142">The Indian and US hospitality markets offer:</p> <ul data-source-line="143-147"> <li data-source-line="143-143">Fragmented ownership landscape with acquisition opportunities<br /><br /></li> <li data-source-line="144-144">Growing domestic and international travel demand<br /><br /></li> <li data-source-line="145-145">Premium valuations for institutionally-owned hotel portfolios (as evidenced by listed peers)<br /><br /></li> <li data-source-line="146-147">Investor appetite for real asset-backed income opportunities</li> </ul> <hr data-source-line="148-148" /> <h2 data-source-line="150-150"><strong>4. Who Are the Peers in This Business?</strong></h2> <p data-source-line="152-152">Sunday Proptech competes in the <strong>institutional hotel ownership and asset management</strong> space. Here's the competitive landscape:</p> <h3 id="listed-indian-hotel-ownership-platforms%3A" tabindex="-1" data-source-line="154-154"><strong>Listed Indian Hotel Ownership Platforms:</strong></h3> <h3 id="1.-chalet-hotels-limited" tabindex="-1" data-source-line="156-156"><strong>1. Chalet Hotels Limited</strong></h3> <ul data-source-line="157-166"> <li data-source-line="157-157"><strong>Market Cap:</strong> ₹21000 Cr (Oct 2025)<br /><br /></li> <li data-source-line="158-158"><strong>Enterprise Value:</strong> ₹23,000 Cr<br /><br /></li> <li data-source-line="159-159"><strong>Portfolio:</strong> 11 luxury properties, 3,314 rooms<br /><br /></li> <li data-source-line="160-160"><strong>FY26E EBITDA:</strong> ₹953 Cr<br /><br /></li> <li data-source-line="161-161"><strong>FY26E Profit:</strong> ₹285 Cr<br /><br /></li> <li data-source-line="162-162"><strong>Valuation Multiples:</strong> 24x EV/EBITDA, 73x P/E<br /><br /></li> <li data-source-line="163-163"><strong>Parent:</strong> K Raheja Corp<br /><br /></li> <li data-source-line="164-164"><strong>Focus:</strong> High-end hotels and commercial properties in gateway cities<br /><br /></li> <li data-source-line="165-166"><strong>Competitive Position:</strong> Premium luxury positioning</li> </ul> <h3 id="2.-ventive-hospitality-limited" tabindex="-1" data-source-line="167-167"><strong>2. Ventive Hospitality Limited</strong></h3> <ul data-source-line="168-178"> <li data-source-line="168-168"><strong>Market Cap:</strong> ₹17,800 Cr<br /><br /></li> <li data-source-line="169-169"><strong>Enterprise Value:</strong> ₹19,410 Cr<br /><br /></li> <li data-source-line="170-170"><strong>Portfolio:</strong> 11 luxury hotels, 2,036 keys (including 3 Maldives properties with 515 rooms)<br /><br /></li> <li data-source-line="171-171"><strong>FY26E EBITDA:</strong> ₹885 Cr<br /><br /></li> <li data-source-line="172-172"><strong>FY26E Profit:</strong> ₹177 Cr<br /><br /></li> <li data-source-line="173-173"><strong>Valuation Multiples:</strong> 22x EV/EBITDA, 100x P/E<br /><br /></li> <li data-source-line="174-174"><strong>Backed by:</strong> Blackstone<br /><br /></li> <li data-source-line="175-175"><strong>Brands:</strong> Marriott, Hilton, Ritz-Carlton<br /><br /></li> <li data-source-line="176-176"><strong>Geography:</strong> Pune, Bengaluru, Maldives<br /><br /></li> <li data-source-line="177-178"><strong>Recent:</strong> Listed recently, showcasing strong investor appetite</li> </ul> <h3 id="3.-samhi-hotels-limited" tabindex="-1" data-source-line="179-179"><strong>3. Samhi Hotels Limited</strong></h3> <ul data-source-line="180-189"> <li data-source-line="180-180"><strong>Market Cap:</strong> ₹4500 Cr<br /><br /></li> <li data-source-line="181-181"><strong>Enterprise Value:</strong> ₹6600 Cr<br /><br /></li> <li data-source-line="182-182"><strong>Portfolio:</strong> ~4,800 keys across 3-star to 5-star segments<br /><br /></li> <li data-source-line="183-183"><strong>FY26E EBITDA:</strong> ₹439 Cr<br /><br /></li> <li data-source-line="184-184"><strong>FY26E Profit:</strong> ₹ 188 Cr<br /><br /></li> <li data-source-line="185-185"><strong>Valuation Multiples:</strong> 15x EV/EBITDA, 32x P/E<br /><br /></li> <li data-source-line="186-186"><strong>Backed by:</strong> Brookfield<br /><br /></li> <li data-source-line="187-187"><strong>Strategy:</strong> Operational turnaround and yield enhancement<br /><br /></li> <li data-source-line="188-189"><strong>Positioning:</strong> Institutional ownership platform</li> </ul> <h3 id="4.-brigade-hotel-ventures-limited" tabindex="-1" data-source-line="190-190"><strong>4. Brigade Hotel Ventures Limited</strong></h3> <ul data-source-line="191-198"> <li data-source-line="191-191"><strong>Market Cap:</strong> ₹3,100 Cr<br /><br /></li> <li data-source-line="192-192"><strong>Enterprise Value:</strong> ₹3,200 Cr<br /><br /></li> <li data-source-line="193-193"><strong>FY25 EBITDA:</strong> ₹ 165 Cr<br /><br /></li> <li data-source-line="194-194"><strong>FY25 Profit:</strong> ₹24 Cr<br /><br /></li> <li data-source-line="195-195"><strong>Valuation Multiples:</strong> 20x EV/EBITDA, 129x P/E<br /><br /></li> <li data-source-line="196-196"><strong>Parent:</strong> Brigade Group<br /><br /></li> <li data-source-line="197-198"><strong>Regional Focus:</strong> South India</li> </ul> <h3 id="peer-average-valuation-range%3A-12-21x-ev%2Febitda" tabindex="-1" data-source-line="199-199"><strong>Peer Average Valuation Range: 15-24x EV/EBITDA</strong></h3> <h3 id="key-differentiators%3A" tabindex="-1" data-source-line="201-201"><strong>Key Differentiators:</strong></h3> <div class="table-container"> </div> <div class="table-container"><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761822133.jpg" alt="" width="633" height="400" /></div> <hr data-source-line="213-213" /> <h2 data-source-line="215-215"><strong>5. How Are Shares Allotted by the Company?</strong></h2> <p data-source-line="217-217">Sunday Proptech has followed a <strong>structured capital raise strategy</strong> with multiple tranches to fund its acquisition pipeline:</p> <h3 id="phase-1%3A-foundation-capital-(april-may-2025)" tabindex="-1" data-source-line="219-219"><strong>Phase 1: Capital (April-May 2025)</strong></h3> <p data-source-line="221-221"><strong>April 28, 2025 - Initial Equity Structure</strong></p> <ul data-source-line="222-224"> <li data-source-line="222-222">2 Crore shares issued as per initial valuation report<br /><br /></li> <li data-source-line="223-224">Foundation shareholder base established</li> </ul> <p data-source-line="225-225"><strong>May 9, 2025 - InCred Private Placement</strong></p> <ul data-source-line="226-230"> <li data-source-line="226-226"><strong>Shares Issued:</strong> 2 Crore<br /><br /></li> <li data-source-line="227-227"><strong>Price:</strong> ₹1 per share<br /><br /></li> <li data-source-line="228-228"><strong>Amount Raised:</strong> ₹2 Crore<br /><br /></li> <li data-source-line="229-230"><strong>Rationale:</strong> Early-stage institutional validation</li> </ul> <h3 id="phase-2%3A-valuation-markup-(july-2025)" tabindex="-1" data-source-line="231-231"><strong>Phase 2: Valuation Markup (July 2025)</strong></h3> <p data-source-line="233-233"><strong>July 28, 2025 - Tattva Fund Placement</strong></p> <ul data-source-line="234-238"> <li data-source-line="234-234"><strong>Shares Issued:</strong> 62.86 Lakh<br /><br /></li> <li data-source-line="235-235"><strong>Price:</strong> ₹52.50 per share<br /><br /></li> <li data-source-line="236-236"><strong>Amount Raised:</strong> ₹33 Crore (approx)<br /><br /></li> <li data-source-line="237-238"><strong>Significance:</strong> <strong>52.5x price increase in 2.5 months</strong> - validates business model and asset quality</li> </ul> <h3 id="phase-3%3A-capital-structure-optimization-(august-2025)" tabindex="-1" data-source-line="239-239"><strong>Phase 3: Capital Structure Optimization (August 2025)</strong></h3> <p data-source-line="241-241"><strong>August 4, 2025 - Bonus Issue</strong></p> <ul data-source-line="242-250"> <li data-source-line="242-242"><strong>Ratio:</strong> Approximately 7:1<br /><br /></li> <li data-source-line="243-243"><strong>Shares Issued:</strong> 32.35 Crore<br /><br /></li> <li data-source-line="244-244"><strong>Price:</strong> ₹0 (bonus to existing shareholders)<br /><br /></li> <li data-source-line="245-250"><strong>Purpose:<br /></strong> <ul data-source-line="246-250"> <li data-source-line="246-246">Improved liquidity<br /><br /></li> <li data-source-line="247-247">Broader shareholder base<br /><br /></li> <li data-source-line="248-248">Lower per-share price for future raises<br /><br /></li> <li data-source-line="249-250">Reward early investors</li> </ul> </li> </ul> <h3 id="phase-4%3A-debt-to-equity-conversion-(october-2025)" tabindex="-1" data-source-line="251-251"><strong>Phase 4: Debt-to-Equity Conversion (October 2025)</strong></h3> <p data-source-line="253-253"><strong>October 1, 2025 - Loan Conversion</strong></p> <ul data-source-line="254-261"> <li data-source-line="254-254"><strong>Shares Issued:</strong> 2.51 Crore<br /><br /></li> <li data-source-line="255-255"><strong>Price:</strong> ₹6.25 per share<br /><br /></li> <li data-source-line="256-256"><strong>Debt Converted:</strong> ₹16.5 Crore<br /><br /></li> <li data-source-line="257-261"><strong>Purpose:<br /></strong> <ul data-source-line="258-261"> <li data-source-line="258-258">Strengthen balance sheet<br /><br /></li> <li data-source-line="259-259">Reduce interest burden<br /><br /></li> <li data-source-line="260-261">Align lender interests with equity upside</li> </ul> </li> </ul> <h3 id="total-capital-raised-(estimated)%3A" tabindex="-1" data-source-line="262-262"><strong>Total Capital Raised (Estimated):</strong></h3> <ul data-source-line="263-267"> <li data-source-line="263-263">InCred Round: ₹2 Cr<br /><br /></li> <li data-source-line="264-264">Tattva Round: ₹33 Cr<br /><br /></li> <li data-source-line="265-265">Debt Conversion: ₹16.5 Cr<br /><br /></li> <li data-source-line="266-267"><strong>Total: ~₹51.5 Crore</strong></li> </ul> <h3 id="current-share-structure%3A" tabindex="-1" data-source-line="268-268"><strong>Current Share Structure:</strong></h3> <ul data-source-line="269-272"> <li data-source-line="269-269"><strong>Total Outstanding Shares:</strong> 37.47 Crore (374,737,010)<br /><br /></li> <li data-source-line="270-270"><strong>Major Events:</strong> 4 capital raises + 1 bonus issue in 6 months<br /><br /></li> <li data-source-line="271-272"><strong>Valuation Trajectory:</strong> ₹1 → ₹52.5 → ₹6.25 (post-bonus adjusted)</li> </ul> <h3 id="allotment-strategy-insights%3A" tabindex="-1" data-source-line="273-273"><strong>Allotment Strategy Insights:</strong></h3> <ol data-source-line="275-279"> <li data-source-line="275-275"><strong>Selective Investor Base:</strong> Chose institutional investors with hospitality/real estate expertise<br /><br /></li> <li data-source-line="276-276"><strong>Milestone-Based Pricing:</strong> Each round tied to operational achievements (property acquisitions)<br /><br /></li> <li data-source-line="277-277"><strong>Liquidity Creation:</strong> Bonus issue prepared company for potential listing<br /><br /></li> <li data-source-line="278-279"><strong>Balance Sheet Management:</strong> Debt-to-equity swap reduced leverage before scale-up</li> </ol> <hr data-source-line="280-280" /> <h2 data-source-line="282-282"><strong>6. Is It Worth Investing at Different Valuations (₹7, ₹10, ₹15)?</strong></h2> <p data-source-line="284-284">This is the <strong>critical investment decision</strong> - let's analyze Sunday Proptech's value proposition at three price points against listed peers:<br /><br />In FY26, Sunday Proptech is expecting a Revenue of INR 38 cr, EBITDA of 25 Cr with 8 Hotels and in FY27, it is expecting a Revenue of INR 177 cr , EBITDA of INR 93 cr and PAT of INR 27 Cr. </p> <h3 id="investment-framework%3A-fy26-ebitda-%3D-%E2%82%B925-crore-(expected)" tabindex="-1" data-source-line="286-286"><strong>Investment Framework: FY26 EBITDA = ₹25 Crore (Expected)</strong></h3> <div class="table-container"> </div> <div class="table-container"><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761819539.jpg" alt="" width="667" height="367" /></div> <hr data-source-line="294-294" /> <h3 id="scenario-a%3A-investment-at-%E2%82%B97-per-share" tabindex="-1" data-source-line="296-296"><strong>Scenario A: Investment at ₹7 per Share</strong></h3> <p data-source-line="298-298"><strong>Valuation: ₹262 Crore Market Cap | 10.5x EBITDA (FY26)</strong></p> <p data-source-line="300-300">✅ <strong>Investment Thesis:</strong></p> <p data-source-line="302-302"><strong>1. Deep Value Entry</strong></p> <ul data-source-line="303-305"> <li data-source-line="303-303">Trading at a <strong>35-55% discount</strong> to listed peers (Samhi: 15x, Ventive: 22x, Chalet: 24x)<br /><br /></li> <li data-source-line="304-305">Samhi Hotels (most comparable) trades at 15x - Sunday would be <strong>30% cheaper</strong></li> </ul> <p data-source-line="306-306"><strong>2. Risk-Adjusted Returns</strong></p> <ul data-source-line="307-310"> <li data-source-line="307-307">Pre-operational risk largely mitigated (8 hotels already operational)<br /><br /></li> <li data-source-line="308-308">Asset backing provides downside protection<br /><br /></li> <li data-source-line="309-310">US properties delivering 35-46% EBITDA margins</li> </ul> <p data-source-line="311-311"><strong>3. Growth Upside</strong></p> <ul data-source-line="312-315"> <li data-source-line="312-312">FY27E EBITDA projected at ₹93 Cr (3.7x growth from FY26)<br /><br /></li> <li data-source-line="313-313">If company maintains 10.5x multiple: Market cap = ₹977 Cr<br /><br /></li> <li data-source-line="314-315"><strong>Potential Return: 370% in 18 months</strong></li> </ul> <p data-source-line="316-316"><strong>4. Re-Rating Catalyst</strong></p> <ul data-source-line="317-319"> <li data-source-line="317-317">As operational track record strengthens, multiple could expand to 12-14x (peer average)<br /><br /></li> <li data-source-line="318-319">At 12x FY27 EBITDA: Market cap = ₹1,116 Cr → <strong>Share price ₹29.8.</strong></li> </ul> <p data-source-line="320-320"><strong>Risk Assessment at ₹7:</strong></p> <ul data-source-line="321-325"> <li data-source-line="321-321">⚠️ Limited liquidity (unlisted)<br /><br /></li> <li data-source-line="322-322">⚠️ Execution risk on 8 pending acquisitions<br /><br /></li> <li data-source-line="323-323">✅ Strong margin of safety<br /><br /></li> <li data-source-line="324-325">✅ Tangible asset backing</li> </ul> <hr data-source-line="328-328" /> <h3 id="scenario-b%3A-investment-at-%E2%82%B910-per-share" tabindex="-1" data-source-line="330-330"><strong>Scenario B: Investment at ₹10 per Share</strong></h3> <p data-source-line="332-332"><strong>Valuation: ₹375 Crore Market Cap | 15.0x EBITDA (FY26)</strong></p> <p data-source-line="334-334">✅ <strong>Investment Thesis:</strong></p> <p data-source-line="336-336"><strong>1. Fair Value Positioning</strong></p> <ul data-source-line="337-339"> <li data-source-line="337-337">Midpoint between Samhi (15x) and Ventive (22x), below Chalet (24x)<br /><br /></li> <li data-source-line="338-339">Reflects growth potential while offering reasonable entry</li> </ul> <p data-source-line="340-340"><strong>2. FY27 Upside</strong></p> <ul data-source-line="341-344"> <li data-source-line="341-341">At 15x multiple on FY27E EBITDA (₹93 Cr): Market cap = ₹1,395 Cr<br /><br /></li> <li data-source-line="342-342"><strong>Share Price: ₹37.2</strong> → <strong>272% return<br /><br /></strong></li> <li data-source-line="343-344">Even at conservative 12x FY27: ₹29.8/share → <strong>198% return</strong></li> </ul> <p data-source-line="345-345"><strong>3. Comparable to Quality Peers</strong></p> <ul data-source-line="346-349"> <li data-source-line="346-346">Similar margin profile to Samhi (institutional, PE-backed)<br /><br /></li> <li data-source-line="347-347">Technology advantage vs. traditional players<br /><br /></li> <li data-source-line="348-349">Dual-geography diversification (India + USA)</li> </ul> <p data-source-line="354-354"><strong>Risk Assessment at ₹10:</strong></p> <ul data-source-line="355-359"> <li data-source-line="355-355">⚠️ Less margin of safety than ₹7 entry<br /><br /></li> <li data-source-line="356-356">⚠️ Needs to execute on growth plan to justify valuation<br /><br /></li> <li data-source-line="357-357">✅ Fair risk-reward for growth investors<br /><br /></li> <li data-source-line="358-359">✅ Better liquidity if lists soon</li> </ul> <hr data-source-line="362-362" /> <h3 id="scenario-c%3A-investment-at-%E2%82%B915-per-share" tabindex="-1" data-source-line="364-364"><strong>Scenario C: Investment at ₹15 per Share</strong></h3> <p data-source-line="366-366"><strong>Valuation: ₹562 Crore Market Cap | 22.5x EBITDA (FY26)</strong></p> <p data-source-line="368-368">⚠️ <strong>Investment Thesis:</strong></p> <p data-source-line="370-370"><strong>1. Premium Valuation</strong></p> <ul data-source-line="371-376"> <li data-source-line="371-371">Trading <strong>around</strong> Chalet (24x) and Ventive (22x)<br /><br /></li> <li data-source-line="372-376">Only justified if Sunday achieves:<br /><br /> <ul data-source-line="373-376"> <li data-source-line="373-373">Superior growth vs. peers<br /><br /></li> <li data-source-line="374-374">Market-leading RevPAR sustainably<br /><br /></li> <li data-source-line="375-376">Faster scale-up (16 hotels by FY27 vs. current 8)</li> </ul> </li> </ul> <p data-source-line="377-377"><strong>2. FY27 Upside Limited</strong></p> <ul data-source-line="378-382"> <li data-source-line="378-378">At 22.5x FY27E EBITDA (₹93 Cr): Market cap = ₹2,093 Cr<br /><br /></li> <li data-source-line="379-379"><strong>Share Price: ₹55.8</strong> → <strong>272% return</strong> (same as ₹10 scenario)<br /><br /></li> <li data-source-line="380-380"><strong>BUT:</strong> Multiple compression risk - peers trade at 12-20x<br /><br /></li> <li data-source-line="381-382">If market re-rates to 15x (fair value): ₹37.2/share → <strong>148% return</strong></li> </ul> <p data-source-line="383-383"><strong>3. Execution Dependency</strong></p> <ul data-source-line="384-387"> <li data-source-line="384-384"><strong>Must deliver</strong> ₹93 Cr FY27 EBITDA (no room for shortfall)<br /><br /></li> <li data-source-line="385-385">Asset acquisition delays directly impact returns<br /><br /></li> <li data-source-line="386-387">Competition from larger players for premium assets</li> </ul> <p data-source-line="398-398"><strong>Risk Assessment at ₹15:</strong></p> <ul data-source-line="399-403"> <li data-source-line="399-399">⚠️ <strong>HIGH</strong> - Premium valuation with limited margin of safety<br /><br /></li> <li data-source-line="400-400">⚠️ Multiple compression risk if growth disappoints<br /><br /></li> <li data-source-line="401-401">⚠️ Illiquidity premium not justified at 22.5x<br /><br /></li> <li data-source-line="402-403">⚠️ Better alternatives exist at this price point (buy Samhi in listed market)</li> </ul> <hr data-source-line="406-406" /> <h3 id="peer-comparison-summary-table%3A" tabindex="-1" data-source-line="408-408"><strong>Peer Comparison Summary Table Based on FY26E Numbers:</strong></h3> <div class="table-container"> </div> <div class="table-container"><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761820152.jpg" alt="" width="645" height="373" /></div> <p data-source-line="419-419">*P/E based on FY26E PAT of ₹10 Cr</p> <hr data-source-line="421-421" /> <h2 data-source-line="434-434"><strong>Key Investment Considerations:</strong></h2> <h3 id="bullish-factors%3A" tabindex="-1" data-source-line="436-436"><strong>Bullish Factors:</strong></h3> <p data-source-line="438-444">✅ <strong>Asset Backing:</strong> Real estate provides tangible value floor<br /><br />✅ <strong>Operational Proof:</strong> 8 US properties delivering 35-46% EBITDA<br /><br />✅ <strong>Technology Moat:</strong> OYO's distribution and revenue management systems<br /><br />✅ <strong>Market Tailwinds:</strong> Travel recovery, premium mid-stay segment growth<br /><br />✅ <strong>Peer Valuations:</strong> Listed comps trading at 12-21x EBITDA<br /><br />✅ <strong>Growth Trajectory:</strong> 3.7x EBITDA growth projected (₹25 Cr → ₹93 Cr)<br /><br />✅ <strong>Dual Geography:</strong> US + India diversification</p> <h3 id="risk-factors%3A" tabindex="-1" data-source-line="446-446"><strong>Risk Factors:</strong></h3> <p data-source-line="448-455">⚠️ <strong>Illiquidity:</strong> Unlisted shares, limited exit options pre-IPO<br /><br />⚠️ <strong>Execution Risk:</strong> 8 pending acquisitions must close on time<br /><br />⚠️ <strong>Capital Requirements:</strong> May need further dilution for expansion<br /><br />⚠️ <strong>Market Risk:</strong> Hospitality cycles, economic downturns<br /><br />⚠️ <strong>Competition:</strong> Larger players (Brookfield, Blackstone) competing for assets<br /><br />⚠️ <strong>OYO Brand Risk:</strong> Reputational challenges from parent company<br /><br />⚠️ <strong>Currency Risk:</strong> 50% revenue from US operations<br /><br />⚠️ <strong>Regulatory Risk:</strong> Real estate and hospitality regulations in multiple countries</p> <hr data-source-line="457-457" /> <h3 id="final-verdict%3A" tabindex="-1" data-source-line="473-473"><strong>Final Verdict:</strong></h3> <p data-source-line="475-475">Sunday Proptech is <strong>NOT for everyone</strong> - but for investors who:</p> <ul data-source-line="476-480"> <li data-source-line="476-476">Can tolerate illiquidity for 18-36 months<br /><br /></li> <li data-source-line="477-477">Believe in OYO's operational capabilities<br /><br /></li> <li data-source-line="478-478">Want exposure to institutionalized hotel ownership<br /><br /></li> <li data-source-line="479-480">Enter at reasonable valuations (₹7-10)</li> </ul> <hr data-source-line="483-483" /> <p data-source-line="485-485"><strong>Disclaimer:</strong> <em>This analysis is based solely on the documents provided and publicly available peer company data. This is not investment advice. Investors should conduct their own due diligence, consult financial advisors, and assess their risk tolerance before making investment decisions in unlisted securities.</em></p> <hr data-source-line="487-487" /> <p data-source-line="489-489"><em><strong>Data Sources:</strong> OYO Assets Presentation (September 2025), Sunday Proptech Share Capital Analysis (October 2025), Secondary research on listed peers by UnlistedZone</em></p>
<p>India’s wealthtech ecosystem continues to attract strong investor interest. Bengaluru-based investment platform <strong>Wint Wealth</strong> is reportedly set to raise about <strong>$20 million</strong> in a new funding round led by <strong>Vertex Ventures Southeast Asia & India</strong>, marking its first major fundraise in over two years.</p> <h3>1. Overview of the Deal</h3> <p>The upcoming round will add to Wint’s earlier <strong>$22 million</strong> capital pool, which includes investors such as <strong>Nikhil Kamath (Zerodha)</strong>, <strong>Kunal Shah (CRED)</strong>, <strong>India Quotient</strong>, <strong>3one4 Capital</strong>, <strong>Arkham Ventures</strong>, <strong>Blume Ventures</strong>, and <strong>Eight Roads Ventures</strong>.</p> <p>This investment reflects the sustained optimism around India’s <strong>wealthtech sector</strong>, one of the most active fintech verticals since 2024. Competing startups like <strong>Dezerv</strong>, <strong>Stable Money</strong>, and <strong>Grip Invest</strong> have also seen fresh rounds, signalling investor confidence in platforms catering to India’s expanding retail and affluent investor base.</p> <h3>2. What Does Wint Wealth Do?</h3> <p>Founded in <strong>2020</strong> by <strong>Ajinkya Kulkarni</strong>, <strong>Abhik Patel</strong>, <strong>Shashank Chimaladari</strong>, and <strong>Anshul Gupta</strong>, Wint Wealth operates as an <strong>online marketplace for fixed-income investments</strong>, regulated by <strong>SEBI</strong> under the <strong>Online Bond Platform Provider (OBPP)</strong> framework.</p> <p>The platform enables retail investors to access <strong>corporate bonds, securitised debt instruments, and NBFC-issued NCDs</strong>—investment options traditionally reserved for institutions. With <strong>yields ranging between 9–12%</strong>, Wint positions itself as a safer, high-return alternative to bank fixed deposits.</p> <p>Retail investors can start with as little as <strong>₹1,000–₹10,000</strong>, depending on the product. Wint claims to conduct rigorous due diligence and has maintained <strong>“zero defaults”</strong> across its offerings.</p> <p>Key competitors include <strong>Stable Money</strong>, <strong>Kuvera</strong>, <strong>Grip Invest</strong>, and <strong>InCred Money</strong>, all vying for market share in India’s growing fixed-income and alternative investment market.</p> <h3>3. Why This Round Matters</h3> <p>The fresh funding will strengthen Wint’s <strong>core bond marketplace</strong> and accelerate expansion into <strong>alternative and debt-based products</strong>. Additionally, it will bolster <strong>Wint Capital</strong>, the company’s <strong>NBFC arm</strong>, enabling it to scale lending operations and enhance technology infrastructure.</p> <p>As competition intensifies among digital investment platforms, this funding comes at a pivotal moment for Wint to consolidate its market position and attract a broader investor base.</p> <h3>4. Regulatory and Business Milestones</h3> <p>Wint Wealth secured <strong>SEBI’s OBPP approval</strong> in 2023, allowing it to list and distribute bonds directly to retail investors. That same year, it obtained <strong>RBI approval</strong> to acquire <strong>Ambium Finserve</strong>, a Chandigarh-based NBFC, gaining a licence to originate and structure credit products.</p> <p>According to company data, <strong>Wint Capital</strong> has disbursed over <strong>₹370 crore in B2B loans</strong> across more than 40 clients, highlighting its growing diversification beyond bond distribution.</p> <h3>5. Vertex Ventures’ Strategic Interest</h3> <p><strong>Vertex Ventures SEA & India</strong>, part of <strong>Temasek Holdings</strong>, has been expanding its footprint in India’s fintech and AI ecosystem. The firm closed its <strong>$541 million Fund V</strong> in September 2023, focusing on early-stage and Series A investments.</p> <p>Its Indian portfolio includes <strong>Kiwi (credit on UPI)</strong>, <strong>Metafin (SME lending)</strong>, <strong>SpotDraft</strong>, <strong>Spyne</strong>, and <strong>Nuuk</strong> in AI and SaaS, along with consumer brands such as <strong>Licious</strong>, <strong>Pilgrim</strong>, and <strong>KukuFM</strong>. Vertex has achieved notable exits through IPOs and acquisitions from firms like <strong>FirstCry</strong> and <strong>GlowRoad</strong>.</p> <p>The fund remains <strong>bullish on SME lending, wealthtech, and sustainable AI startups</strong>, driven by expanding exit opportunities in India.</p> <h3>6. What’s Fueling the Wealthtech Boom?</h3> <p>India’s <strong>wealthtech sector</strong> has emerged as one of the most resilient fintech categories over the past 18 months. Investors are increasingly backing platforms offering <strong>diversified investment options</strong> across mutual funds, bonds, and alternative assets.</p> <p>Growth is driven by:</p> <ul data-spread="false"> <li> <p>A rapidly expanding <strong>affluent and retail investor base</strong></p> </li> <li> <p>Rising <strong>financial literacy and digital adoption</strong></p> </li> <li> <p>Clear <strong>regulatory frameworks</strong> for online bond platforms</p> </li> </ul> <p>Recent highlights include <strong>Dezerv’s ₹350 crore ($42 million) round</strong> led by Premji Invest and Accel, and <strong>Stable Money’s upcoming round from Peak XV</strong>. Strategic deals such as <strong>Groww’s $150 million acquisition of Fisdom</strong> and <strong>CRED’s acquisition of Kuvera</strong> underline growing consolidation and long-term investor confidence.</p> <h3>Conclusion</h3> <p>Wint Wealth’s $20 million round led by Vertex Ventures reinforces the momentum in India’s wealthtech landscape. With regulatory clarity, a growing investor base, and institutional capital flowing in, the sector is poised for sustained expansion.</p> <p>As Wint strengthens its lending and bond distribution capabilities, it stands well-positioned to capture the next phase of India’s fixed-income investment revolution.</p> <h3><strong>Disclaimer</strong></h3> <p>UnlistedZone is not a SEBI-registered Research Analyst or Investment Advisor. All information provided on our platform is strictly for educational and informational purposes. We do not offer investment advice or stock recommendations. Investors are advised to conduct their own due diligence or consult a SEBI-registered advisor. Investments in unlisted and pre-IPO shares are subject to market risks including illiquidity and volatility. UnlistedZone does not assure any returns or accept liability for investment outcomes based on this report.</p>
<p>SBI General Insurance delivered a resilient performance in the first half of FY26, maintaining its growth momentum in premium collections while improving underwriting profitability. Despite a dip in investment income due to volatile markets, the company showcased operational strength through improved claim ratios and a significantly higher operating profit.</p> <h2>1. Premium Growth Remains Strong</h2> <p>SBI General’s <strong>Gross Written Premium (GWP)</strong> grew <strong>10.7% YoY</strong> to ₹7,376 crore in 6MFY26 from ₹6,663 crore in the same period last year. This indicates continued traction across both retail and corporate segments, particularly in motor and health portfolios.</p> <p>The <strong>Net Written Premium (NEP)</strong> increased <strong>11.6% YoY</strong> to ₹4,547 crore, reflecting effective risk retention and portfolio expansion. Premium Earned rose <strong>10.8% YoY</strong> to ₹4,725 crore, suggesting consistent revenue flow from prior policy renewals and new business growth.</p> <p>While the growth rate has moderated compared to FY25 (15.7%), it still exceeds the industry average of around 8–9%, highlighting SBI General’s ability to sustain business momentum despite competitive pricing pressures.</p> <h2>2. Financial Performance Overview</h2> <h2><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761655194.jpg" alt="" width="818" height="842" /></h2> <h2>3. Ratio Analysis and Interpretation</h2> <h2><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761719214.jpg" alt="" width="810" height="735" /></h2> <h2>4. Operational Efficiency</h2> <p><strong>Claims and Costs:</strong></p> <ul data-spread="false"> <li> <p>Claim cost rose only 2.4% YoY, much slower than premium growth, driving down the claim ratio.</p> </li> <li> <p>Commission expenses increased sharply, suggesting stronger focus on distribution expansion.</p> </li> <li> <p>Operating expenses grew 11.3%, primarily due to marketing and digital initiatives.</p> </li> </ul> <p><strong>Interpretation:</strong> The decline in claim ratio is the standout positive. SBI General is paying out a smaller portion of premiums as claims, indicating improved pricing and claim settlement processes. The combined ratio improving to 108.9% suggests operational efficiency gains, even if underwriting losses persist.</p> <h2>5. Investment Income Weakness</h2> <p>Investment income fell <strong>49.2% YoY</strong>, significantly impacting the bottom line. Like most insurers, SBI General relies on investment returns to balance underwriting results. The fall was driven by market volatility and lower realized gains. However, a rebound in yields and equity markets could reverse this trend in H2 FY26.</p> <h2>6. Overall Business Health and Outlook</h2> <ul data-spread="false"> <li> <p><strong>Operationally Strong:</strong> Improved claim and combined ratios demonstrate underwriting maturity.</p> </li> <li> <p><strong>Growth Sustained:</strong> Premiums growing in double digits despite slower market expansion.</p> </li> <li> <p><strong>Expense Pressure:</strong> Higher costs are strategic investments in scale and technology.</p> </li> <li> <p><strong>Investment Drag Temporary:</strong> Market-driven fluctuations; expected recovery in H2 FY26.</p> </li> </ul> <p><strong>Outlook:</strong> SBI General is well-positioned for margin improvement through disciplined underwriting and controlled claims. The focus on retail health, motor, and SME lines provides a stable revenue base.</p> <h2>7. Conclusion</h2> <p>SBI General Insurance’s 6MFY26 results highlight a strong operational recovery. The company is evolving from growth-driven expansion to profitability-driven sustainability. Lower claim ratios, improved operating profits, and stable premium growth underline a healthy core business. While investment income volatility limited PAT growth, the fundamentals remain solid, positioning SBI General favorably for future growth and potential IPO readiness.</p> <h3>Disclaimer:</h3> <p>UnlistedZone is not a SEBI-registered Research Analyst or Investment Advisor. All information provided on our platform is strictly for educational and informational purposes. We do not offer investment advice or stock recommendations. Investors are advised to conduct their own due diligence or consult a SEBI-registered advisor. Investments in unlisted and pre-IPO shares are subject to market risks including illiquidity and volatility. UnlistedZone does not assure any returns or accept liability for investment outcomes based on this report.</p>
<p><strong>Eyewear retailer Lenskart Solutions Limited</strong> has delivered a strong performance for the quarter ended June 30, 2025 (Q1 FY26), posting a <strong>net profit of ₹61.2 crore</strong>, compared to a <strong>loss of ₹10.9 crore</strong> in the same quarter last year. The company’s robust growth comes just days before its much-awaited <strong>₹2,150 crore IPO</strong>.</p> <h2>1. Financial Performance Overview</h2> <p>Lenskart’s <strong>revenue from operations</strong> jumped <strong>24.6% year-on-year</strong> to <strong>₹1,894.5 crore</strong> from ₹1,520.4 crore in Q1 FY25, driven by strong demand across both online and offline channels and steady expansion in domestic and international markets.</p> <p><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761563347.jpg" alt="" width="600" height="453" /></p> <p>The company’s <strong>profit before tax (PBT)</strong> stood at <strong>₹75.9 crore</strong>, compared to a <strong>loss of ₹12.4 crore</strong> a year ago. Total income rose to <strong>₹1,934.1 crore</strong>, while total expenses increased to <strong>₹1,858 crore</strong>, reflecting higher marketing and expansion costs.</p> <h2>2. Strong Operating Leverage and Cost Discipline</h2> <p>Lenskart’s <strong>EBITDA</strong> surged to <strong>₹336.6 crore</strong> from <strong>₹183.4 crore</strong> in Q1 FY25, supported by higher sales productivity, improved product margins, and cost discipline.</p> <ul data-spread="false"> <li> <p><strong>Finance costs:</strong> ₹41 crore</p> </li> <li> <p><strong>Depreciation & amortisation:</strong> ₹181.2 crore</p> </li> <li> <p><strong>Product Margin:</strong> 68.1% (flat YoY)</p> </li> </ul> <p>The company attributed the improvement to better operating leverage from its growing store network and investments in technology infrastructure.</p> <h2>3. India and International Business Breakdown</h2> <p> </p> <p><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761563369.jpg" alt="" width="548" height="273" />The <strong>India business</strong> continues to lead performance with a 25% year-on-year revenue growth. Meanwhile, the <strong>international segment</strong> — covering the Middle East and Southeast Asia — grew over 26%, underlining Lenskart’s accelerating global presence.</p> <h2>4. Operational Highlights</h2> <p><strong><img src="https://unlistedzone.com/storage/knowledge-logo/app_image-1761563582.jpg" alt="" width="600" height="309" /></strong></p> <p><strong>Highlights:</strong></p> <ul data-spread="false"> <li> <p>Transacting customer accounts: <strong>4.43 million</strong> (up from 3.41 million YoY)</p> </li> <li> <p>Eyewear units sold: <strong>7.8 million</strong> (up from 6.35 million YoY)</p> </li> <li> <p>Store count: <strong>2,806</strong> (up from 2,435 YoY)</p> </li> <li> <p>Operating cash flow: <strong>₹283 crore</strong></p> </li> </ul> <p>Lenskart’s expanding footprint, coupled with efficient store performance, continues to strengthen its omnichannel growth strategy.</p> <h2>5. Upcoming IPO Details</h2> <p>Lenskart’s IPO is among the most anticipated public issues in 2025. The <strong>anchor round opens on October 30</strong>, followed by the <strong>public offer between October 31 and November 4, 2025</strong>.</p> <p>The offering includes:</p> <ul data-spread="false"> <li> <p><strong>Fresh issue:</strong> ₹2,150 crore</p> </li> <li> <p><strong>Offer for sale (OFS):</strong> 12.76 crore shares by existing investors like <strong>SoftBank, Kedaara Capital, ChrysCapital, and KKR</strong></p> </li> </ul> <h2>Key Takeaway</h2> <p>Lenskart’s Q1 FY26 performance reflects strong demand momentum, improved profitability, and effective cost control — signaling a confident entry into the public markets. With a rapidly expanding store network and rising global presence, the company is well-positioned to sustain its growth trajectory.</p> <div contenteditable="false"><hr /></div> <p><strong>Disclaimer:</strong> UnlistedZone is not a SEBI-registered Research Analyst or Investment Advisor. All information provided on our platform is strictly for educational and informational purposes. We do not offer investment advice or stock recommendations. Investors are advised to conduct their own due diligence or consult a SEBI-registered advisor. Investments in unlisted and pre-IPO shares are subject to market risks including illiquidity and volatility. UnlistedZone does not assure any returns or accept liability for investment outcomes based on this report.</p>
<p data-start="254" data-end="564">PharmEasy’s parent, <strong data-start="274" data-end="290">API Holdings</strong>, has been struggling for the last two years with tight liquidity, debt refinancing challenges, and delayed IPO plans. But now, a major promoter transaction in <strong data-start="450" data-end="476">Thyrocare Technologies</strong>, the most profitable business under its umbrella, might finally provide breathing room.</p> <p data-start="566" data-end="834">On 24th October 2025, <strong data-start="588" data-end="626">Docon Technologies Private Limited</strong>, a 100% subsidiary of API Holdings and the promoter of Thyrocare, <strong data-start="693" data-end="719">sold ~53.3 lakh shares</strong> through market trades.<br data-start="742" data-end="745" />Transaction value: <strong data-start="764" data-end="781">₹667.69 crore</strong><br data-start="781" data-end="784" />Average sale price: <strong data-start="804" data-end="824">₹1,252 per share</strong> (rounded)</p> <p data-start="836" data-end="895">This represents around <strong data-start="859" data-end="881">10% stake dilution</strong> in Thyrocare.</p> <p data-start="897" data-end="1071">With a market cap of ~₹6,700 crore, Thyrocare remains an attractive, cash-generating asset — something API Holdings critically needs while navigating its turnaround strategy.</p> <hr data-start="1073" data-end="1076" /> <h2 data-start="1078" data-end="1124"><strong data-start="1081" data-end="1124">1. Thyrocare: The Crown Jewel of PharmEasy</strong></h2> <p data-start="1126" data-end="1289">API Holdings entered into diagnostics with the <strong data-start="1173" data-end="1209">acquisition of Thyrocare in 2021</strong>, paying a steep premium then. Despite the struggling digital pharmacy business:</p> <p data-start="1291" data-end="1448"><strong>1</strong>. Thyrocare continues to be profitable<br data-start="1329" data-end="1332" /><strong>2</strong>. Generates steady cash flows<br data-start="1361" data-end="1364" /><strong>3.</strong> Strong brand in preventive diagnostics<br data-start="1404" data-end="1407" /><strong>4</strong>. Franchise-led model ensures scalability</p> <p data-start="1450" data-end="1593">While PharmEasy’s core B2C e-pharmacy business is margin-thin and regulatory-heavy, Thyrocare has been <strong data-start="1553" data-end="1579">the financial backbone</strong> of the group.</p> <hr data-start="1595" data-end="1598" /> <h2 data-start="1600" data-end="1640"><strong data-start="1603" data-end="1640">2. Why Did Docon Sell the Stake Now?</strong></h2> <p data-start="1642" data-end="1696">The financial strain on API Holdings has been visible:</p> <ul data-start="1698" data-end="1941"> <li data-start="1698" data-end="1766"> <p data-start="1700" data-end="1766">IPO plans stalled due to market volatility and governance concerns</p> </li> <li data-start="1767" data-end="1818"> <p data-start="1769" data-end="1818">High operational costs in e-pharmacy distribution</p> </li> <li data-start="1819" data-end="1886"> <p data-start="1821" data-end="1886">Competition from Tata 1mg, Netmeds, and Reliance’s Digital Health</p> </li> <li data-start="1887" data-end="1941"> <p data-start="1889" data-end="1941">Need for debt servicing and working capital infusion</p> </li> </ul> <p data-start="1943" data-end="1995">This <strong data-start="1948" data-end="1975">₹668 crore monetization</strong> is likely aimed at:</p> <ul data-start="1997" data-end="2161"> <li data-start="1997" data-end="2023"> <p data-start="1999" data-end="2023"><strong data-start="1999" data-end="2023">Reducing debt burden</strong></p> </li> <li data-start="2024" data-end="2063"> <p data-start="2026" data-end="2063">Strengthening <strong data-start="2040" data-end="2063">net working capital</strong></p> </li> <li data-start="2064" data-end="2115"> <p data-start="2066" data-end="2115">Supporting <strong data-start="2077" data-end="2115">sustainable business restructuring</strong></p> </li> <li data-start="2116" data-end="2161"> <p data-start="2118" data-end="2161">De-risking dependence on external fundraise</p> </li> </ul> <p data-start="2163" data-end="2253">The market is interpreting this as a <strong data-start="2200" data-end="2233">strategic damage-control move</strong>, not distress sale.</p> <hr data-start="2255" data-end="2258" /> <h2 data-start="2260" data-end="2296"><strong data-start="2263" data-end="2296">3. Will More Stake Sales Follow?</strong></h2> <p data-start="2298" data-end="2438">Currently, Docon owns <strong data-start="2320" data-end="2330">71.06%</strong> stake in Thyrocare. Even after this sale, the promoter holding remains significantly high — giving options:</p> <div class="_tableContainer_1rjym_1"> <div class="group _tableWrapper_1rjym_13 flex w-fit flex-col-reverse" tabindex="-1"> <table class="w-fit min-w-(--thread-content-width)" style="width: 49.1166%;" data-start="2440" data-end="2610"> <thead data-start="2440" data-end="2483"> <tr data-start="2440" data-end="2483"> <th style="text-align: center; width: 54.4866%;" data-start="2440" data-end="2454" data-col-size="sm">Particulars</th> <th style="text-align: center; width: 29.6896%;" data-start="2454" data-end="2468" data-col-size="sm">Before Sale</th> <th style="text-align: center; width: 15.9614%;" data-start="2468" data-end="2483" data-col-size="sm">After Sale*</th> </tr> </thead> <tbody data-start="2525" data-end="2610"> <tr data-start="2525" data-end="2572"> <td style="text-align: center; width: 54.4866%;" data-start="2525" data-end="2555" data-col-size="sm">Promoter stake in Thyrocare</td> <td style="text-align: center; width: 29.6896%;" data-col-size="sm" data-start="2555" data-end="2564">71.06%</td> <td style="text-align: center; width: 15.9614%;" data-col-size="sm" data-start="2564" data-end="2572">~61%</td> </tr> <tr data-start="2573" data-end="2610"> <td style="text-align: center; width: 54.4866%;" data-start="2573" data-end="2590" data-col-size="sm">Value unlocked</td> <td style="text-align: center; width: 29.6896%;" data-col-size="sm" data-start="2590" data-end="2596">Nil</td> <td style="text-align: center; width: 15.9614%;" data-col-size="sm" data-start="2596" data-end="2610">₹668 crore</td> </tr> </tbody> </table> </div> </div> <p data-start="2612" data-end="2644">*Approximate post-sale estimate</p> <p data-start="2646" data-end="2738">Docon can still liquidate a further portion <strong data-start="2690" data-end="2737">without losing board or operational control</strong>.</p> <p data-start="2740" data-end="2803">This optionality is critical for <strong data-start="2773" data-end="2802">PharmEasy’s survival plan</strong>.</p> <hr data-start="2805" data-end="2808" /> <h2 data-start="2810" data-end="2849"><strong data-start="2813" data-end="2849">4. What Does It Mean for Investors?</strong></h2> <h3 data-start="2851" data-end="2894">1. Positive for API Holdings (PharmEasy)</h3> <ul data-start="2895" data-end="3048"> <li data-start="2895" data-end="2912"> <p data-start="2897" data-end="2912">Liquidity boost</p> </li> <li data-start="2913" data-end="2948"> <p data-start="2915" data-end="2948">Improved confidence among lenders</p> </li> <li data-start="2949" data-end="2983"> <p data-start="2951" data-end="2983">Potential revival path from FY26</p> </li> <li data-start="2984" data-end="3048"> <p data-start="2986" data-end="3048">If profitability improves, <strong data-start="3013" data-end="3048">IPO revival may return to radar</strong></p> </li> </ul> <h3 data-start="3050" data-end="3103">2. Neutral-to-Cautious for Thyrocare shareholders</h3> <ul data-start="3104" data-end="3235"> <li data-start="3104" data-end="3140"> <p data-start="3106" data-end="3140">No change in business fundamentals</p> </li> <li data-start="3141" data-end="3186"> <p data-start="3143" data-end="3186">Market may react to promoter stake dilution</p> </li> <li data-start="3187" data-end="3235"> <p data-start="3189" data-end="3235">Future promoter exits could create uncertainty</p> </li> </ul> <h3 data-start="3237" data-end="3261">3. Watchlist Factors</h3> <ul data-start="3262" data-end="3423"> <li data-start="3262" data-end="3319"> <p data-start="3264" data-end="3319">Utilization of funds must be <strong data-start="3293" data-end="3319">efficient and targeted</strong></p> </li> <li data-start="3320" data-end="3367"> <p data-start="3322" data-end="3367">E-pharmacy regulatory scenario remains a risk</p> </li> <li data-start="3368" data-end="3423"> <p data-start="3370" data-end="3423">Further stake sale may be required if losses continue</p> </li> </ul> <p data-start="3425" data-end="3500">Investor sentiment will largely depend on <strong data-start="3467" data-end="3499">how API deploys this capital</strong>.</p> <hr data-start="3502" data-end="3505" /> <h2 data-start="3507" data-end="3556"><strong data-start="3510" data-end="3556">5. Can FY26 Become PharmEasy’s Comeback Year?</strong></h2> <p data-start="3558" data-end="3611">There are visible restructuring initiatives underway:</p> <ul data-start="3613" data-end="3891"> <li data-start="3613" data-end="3650"> <p data-start="3615" data-end="3650">Focus on high-margin private labels</p> </li> <li data-start="3651" data-end="3715"> <p data-start="3653" data-end="3715">Integration of diagnostic + medicine distribution supply chain</p> </li> <li data-start="3716" data-end="3770"> <p data-start="3718" data-end="3770">Increasing efficiencies in logistics and procurement</p> </li> <li data-start="3771" data-end="3834"> <p data-start="3773" data-end="3834">Gradual reduction in discounts and customer acquisition spend</p> </li> <li data-start="3835" data-end="3891"> <p data-start="3837" data-end="3891">Partnerships with offline pharmacies → <strong data-start="3876" data-end="3891">B2B scaling</strong></p> </li> </ul> <p data-start="3893" data-end="3920">If API Holdings manages to:</p> <p data-start="3922" data-end="4009"><strong>1.</strong> reduce cash burn<br data-start="3940" data-end="3943" /><strong>2</strong>. bring margins closer to peers<br data-start="3974" data-end="3977" /><strong>3</strong>. drive hybrid phygital growth</p> <p data-start="4011" data-end="4077">…then FY26 could be a <strong data-start="4033" data-end="4050">turning point</strong> after two difficult years.</p> <hr data-start="4079" data-end="4082" /> <h2 data-start="4084" data-end="4118"><strong data-start="4087" data-end="4118">6. Unlisted Market Perspective</strong></h2> <p data-start="4120" data-end="4191">PharmEasy’s unlisted valuation has collapsed drastically from its peak:</p> <div class="_tableContainer_1rjym_1"> <div class="group _tableWrapper_1rjym_13 flex w-fit flex-col-reverse" tabindex="-1"> <table class="w-fit min-w-(--thread-content-width)" style="width: 46.5885%;" data-start="4193" data-end="4341"> <thead data-start="4193" data-end="4222"> <tr data-start="4193" data-end="4222"> <th style="text-align: center; width: 61.1441%;" data-start="4193" data-end="4201" data-col-size="sm">Stage</th> <th style="text-align: center; width: 38.7338%;" data-start="4201" data-end="4222" data-col-size="sm">Approx. Valuation</th> </tr> </thead> <tbody data-start="4251" data-end="4341"> <tr data-start="4251" data-end="4282"> <td style="text-align: center; width: 61.1441%;" data-start="4251" data-end="4265" data-col-size="sm">Peak (2021)</td> <td style="text-align: center; width: 38.7338%;" data-start="4265" data-end="4282" data-col-size="sm">~$5.6 billion</td> </tr> <tr data-start="4283" data-end="4341"> <td style="text-align: center; width: 61.1441%;" data-start="4283" data-end="4314" data-col-size="sm">Latest unlisted transactions</td> <td style="text-align: center; width: 38.7338%;" data-col-size="sm" data-start="4314" data-end="4341">~$2.5–3.0 billion range</td> </tr> </tbody> </table> </div> </div> <p data-start="4343" data-end="4364">With fresh liquidity:</p> <ul data-start="4366" data-end="4507"> <li data-start="4366" data-end="4394"> <p data-start="4368" data-end="4394"><strong data-start="4368" data-end="4394">Solvency risks decline</strong></p> </li> <li data-start="4395" data-end="4442"> <p data-start="4397" data-end="4442"><strong data-start="4397" data-end="4442">Investor confidence may gradually recover</strong></p> </li> <li data-start="4443" data-end="4507"> <p data-start="4445" data-end="4507">New institutional funding could reopen at realistic valuations</p> </li> </ul> <p data-start="4509" data-end="4575">But recovery <strong data-start="4522" data-end="4544">won’t be overnight</strong> — execution discipline is key.</p> <hr data-start="4577" data-end="4580" /> <h2 data-start="4582" data-end="4599"><strong data-start="4585" data-end="4599">Conclusion</strong></h2> <p data-start="4601" data-end="4760">The 10% promoter stake sale in Thyrocare is more than just a financial transaction — it could be <strong data-start="4698" data-end="4759">the first step toward PharmEasy’s financial stabilization</strong>.</p> <p data-start="4762" data-end="4943">If the proceeds are used wisely to optimize operations and reduce debt, <strong data-start="4834" data-end="4897">API Holdings might finally steer its business back on track</strong> and target a return to profitability in FY26.</p> <p data-start="4945" data-end="5119"><strong data-start="4945" data-end="5119">For investors, the next 2–3 quarters will be crucial indicators of whether this move truly marks the beginning of PharmEasy’s turnaround story — or just temporary relief</strong></p>
Indicative prices, company research and your enquiries — in your pocket. Get price notes on the names you follow and reach our team from anywhere.


