SK Finance H1 FY27: The Lender That Stopped Running (and Still Got Richer)
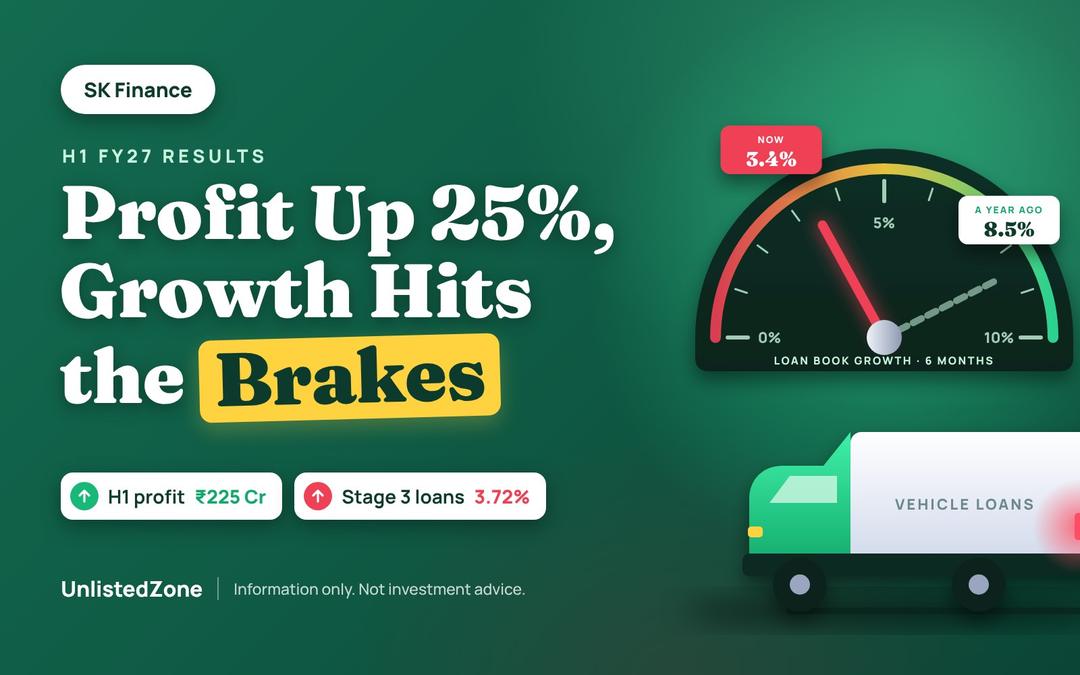
In today's story, we look at how Jaipur-based SK Finance grew its profit 25% in the first half of FY27 (April–September 2026) while its loan book barely moved.
Meet Ramesh. He runs a second-hand truck near Bhilwara. He has no salary slip and no credit score, so no bank would lend to him. SK Finance said yes.
That has been SK Finance's business since 1994: vehicle and small-business loans in rural and semi-urban India. It's an NBFC, a lender that isn't a bank. It borrows from banks and bond investors and lends that money on at higher rates. Its shares aren't listed, but its bonds are, so it publishes results every six months.
The latest results contain a puzzle:
Profit: up 25% to ₹225 crore
Loan book: up just 3.4% in six months, against 8.5% a year ago
So how does a lender that slowed down end up making more money? Let's find out.
H1 FY27 is April–September 2026, and H1 FY26 is the same six months a year earlier.
₹ crore | H1 FY27 | H1 FY26 | YoY change |
|---|---|---|---|
| Interest income | 1,284.3 | 1,192.3 | +7.7% |
| Fees & commission | 94.1 | 64.2 | +46.7% |
| Gain on selling loans (assignment) | 117.6 | 89.0 | +32.0% |
| Total income | 1,497.7 | 1,351.5 | +10.8% |
| Finance cost (interest paid) | 556.5 | 554.8 | +0.3% |
| Net interest income (NII) | 727.9 | 637.5 | +14.2% |
| Operating expenses | 432.4 | 387.3 | +11.6% |
| Pre-provision operating profit | 505.1 | 409.4 | +23.4% |
| Provisions for bad loans | 205.2 | 175.0 | +17.3% |
| Profit after tax | 224.6 | 179.2 | +25.3% |
| EPS, diluted (₹) | 16.57 | 13.25 | +25.1% |
| Cost-to-income ratio | 46.1% | 48.6% | –250 bps |
The takeaway: profit grew 25%, but interest income grew only 7.7%. Something else did the heavy lifting. And in just six months, SK Finance has earned 52% of last year's full-year profit.
Think of an NBFC as a shop that sells money. It buys money wholesale from banks and bondholders, then sells it retail to borrowers. Its profit is the gap between the two prices.
Here's what happened this year:
Wholesale got cheaper: cost of funds fell from 9.3% to 8.6%. Borrowings rose 7%, but the interest bill stayed flat at ₹556 crore. More bond funding helped: debt securities rose from ₹2,446 crore to ₹3,752 crore.
Retail got cheaper too: the yield on loans slipped from 19.3% to 18.3%.
The gap is measured by NIM (net interest margin). It's net interest income divided by the money lent out.
Annualised, on average balances | H1 FY27 | H1 FY26 | FY26 |
|---|---|---|---|
| Yield on loans | 18.3% | 19.3% | 19.1% |
| Cost of funds | 8.6% | 9.3% | 9.2% |
| Spread | 9.7% | 10.0% | 10.0% |
| NIM (NII ÷ average loans) | 10.35% | 10.33% | 10.41% |
| NIM (NII ÷ average interest-earning assets) | 8.81% | 8.40% | 8.60% |
| Net total income ÷ average loans (counts fees and loan-sale gains) | 13.33% | 12.91% | 13.31% |
What the table shows:
NIM on loans is flat at about 10.4%. The lower yield and the lower funding cost cancelled each other out.
NIM on all earning assets rose from 8.4% to 8.8%. Idle cash sitting in FDs at 6–7% moved into loans earning about 18%.
Costs are under control. Cost-to-income fell from 48.6% to 46%, so operating profit grew 23% while interest income grew 8%.
Growth is where the story slows down.
₹ crore | Sep-26 | Sep-25 | YoY | Mar-26 | Mar-25 |
|---|---|---|---|---|---|
| Loans (on books) | 14,302 | 12,850 | +11.3% | 13,830 | 11,841 |
| Cash + bank + investments | 2,459 | 2,724 | –9.7% | 2,462 | 2,944 |
| Total assets | 17,663 | 16,297 | +8.4% | 17,152 | 15,419 |
| Borrowings | 13,110 | 12,283 | +6.7% | 12,820 | 11,604 |
| Net worth | 4,207 | 3,707 | +13.5% | 3,982 | 3,502 |
Slower lending: loans grew 3.4% in H1 FY27, against 8.5% in H1 FY26. Net new lending fell from ₹1,157 crore to ₹676 crore.
More loan sales: SK Finance sold ₹754 crore of healthy loans to banks, up from ₹531 crore. This is called assignment. The company books the profit upfront and frees up capital.
A big profit contributor: gains from these sales came to ₹118 crore, almost 40% of pre-tax profit.
Strip those gains out and Q2 pre-tax profit falls from ₹161 crore to about ₹106 crore. That's still well up on about ₹68 crore a year ago, so the core business did grow. But a big slice of profit depends on how many loans buyers want to take each quarter.
Say Ramesh misses three EMIs. His loan is now "bad", but lenders measure bad loans in two ways:
Stage 3 (accounting rules, Ind AS): looks at how overdue a loan is right now. If Ramesh is 90+ days behind today, he's in. If he pays up, he's out.
GNPA (RBI rules): stickier. Once Ramesh is tagged an NPA, he stays tagged until he clears every rupee he owes, not just enough to get under 90 days.
Here's how SK Finance stacks up:
Sep-26 | Sep-25 | Change | |
|---|---|---|---|
| Provision coverage (Stage 3) | 39.6% | 39.9% | flat |
| Gross NPA (RBI) | 4.71% | 4.77% | –6 bps |
| Net NPA (RBI) | 3.20% | 3.27% | –7 bps |
| Credit cost (annualised) | 2.92% | 2.84% | +8 bps |
| Bad loans sold to ARCs in the half (₹ cr) | 225 | 220 | similar |
What stands out:
Stage 3 jumped from 2.81% to 3.72%, while RBI GNPA stayed flat at about 4.7%. That points to fresh stress, not old problem loans.
Bad loans are sold every six months to asset reconstruction companies (ARCs): ₹225 crore this half and ₹220 crore a year ago. The ARC pays mostly in security receipts, which pay out only if it recovers the money. SK Finance holds ₹259 crore of these, ₹120 crore of them unrated. So the reported NPA looks better than the underlying book.
Provision cover is thin at about 40%. Secured lenders can repossess the vehicle, but there's less cushion if recoveries disappoint.
Here's an odd complaint to make about a lender: it might be too safe.
H1 FY27 | H1 FY26 | FY26 | |
|---|---|---|---|
| Capital adequacy (CRAR) | 25.3% | 27.3% | – |
| Liquidity coverage ratio | 152% | 250% | – |
| Debt / equity | 3.13x | 3.32x | – |
| ROA (annualised) | 2.58% | 2.26% | 2.65% |
| ROE (annualised) | 11.0% | 9.9% | 11.5% |
Capital: 25% of risk-weighted loans, against RBI's 15% minimum
Leverage: about ₹3 borrowed for every ₹1 of equity, while many vehicle lenders run at 4–5x
Result: return on assets is a healthy 2.6%, but ROE is stuck around 11%
The fix is to grow faster and put that capital to work. Which brings us back to the slowdown.
SK Finance's H1 FY27 is a story of a lender that got more efficient, not bigger.
What's working
Profit up 25%, and pre-provision profit up 23%
Cost of funds down about 70 bps as bond borrowing ramps up
Steady NIM of about 10.4% on loans, and a better 8.8% on all earning assets
Cost-to-income improved to 46%
Fee income up 47%
What to watch
Loan growth slowed to 3.4% in six months, from 8.5% a year earlier
Almost 40% of pre-tax profit comes from selling loans
Gross Stage 3 jumped from 2.81% to 3.72%, a sign of fresh stress
Regular ARC sales and ₹259 crore of security receipts keep the reported NPA flattering
ROE of about 11% is held down by a very large capital cushion
For Ramesh, SK Finance is still the lender that said yes when the banks didn't. For investors, the question for H2 is simple: can it start lending faster again without the Stage 3 number creeping higher? If it manages both, that 11% ROE has room to climb. If growth stays slow, the profit engine depends on cheap funding and loan sales, and neither lasts forever.
Note: Figures come from SK Finance's unaudited results for the half-years ended 30 September 2026 and 30 September 2025. NIM, yield, cost of funds, credit cost, ROA and ROE are our own calculations on average opening and closing balances, annualised. This is not investment advice.