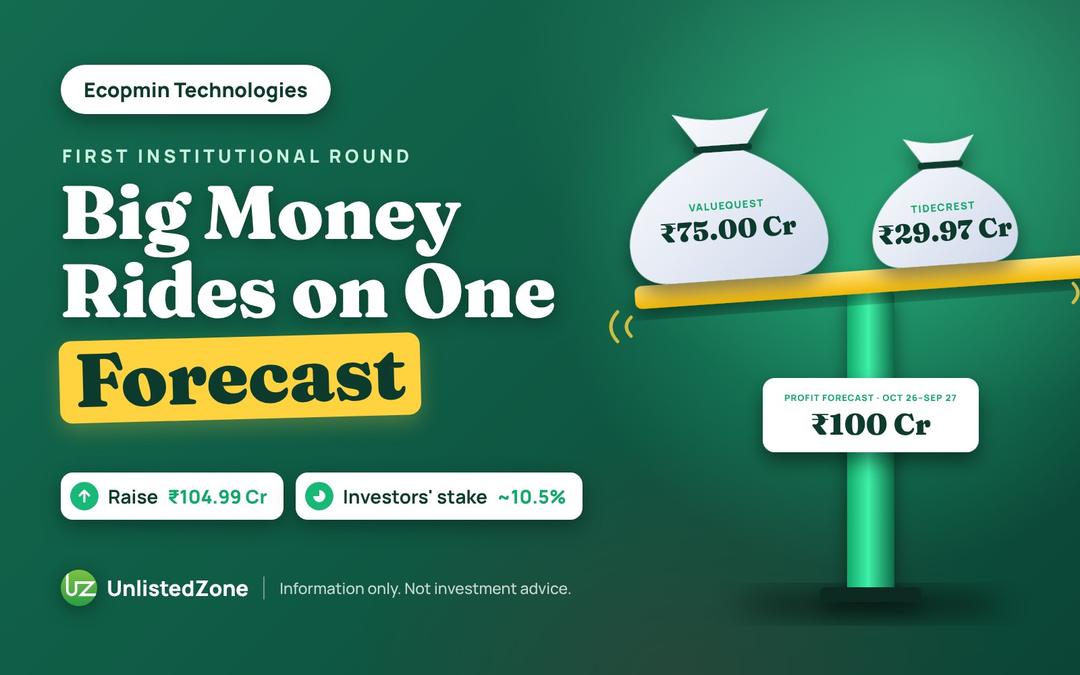
Ecopmin Technologies Private Limited, a Chennai-based company, is raising ₹104.99 crore (about ₹105 crore) in its first institutional round. The money comes from ValueQuest Tristar Fund and Tidecrest Partners, a Dharamshi family vehicle. The deal values the company at ₹1,000 crore post-money.
Shareholders vote on the round at an Extraordinary General Meeting (EGM) on 21 November 2026 in Chennai. This blog walks through the EGM notice: who is investing, at what price, and what it means for existing shareholders.
Two investors will subscribe to 28,300 Series A Compulsorily Convertible Preference Shares (CCPS) at ₹37,102 each.
Investor | Type | Series A CCPS | Amount (₹ cr) |
|---|---|---|---|
| ValueQuest Tristar Fund | Alternative Investment Fund | 20,215 | 75.00 |
| Tidecrest Partners (via Kalpraj Damji Dharamshi, Harsha Hemang Dharamshi and Paolomi Kalpraj Dharamshi) | Partnership firm | 8,085 | 29.97 |
| Total | 28,300 | 104.99 |
ValueQuest is the investment firm founded by well-known investor Ravi Dharamshi. His name does not appear in the notice itself. The ₹75 crore comes through the fund, not from him personally. The promoters and directors are not investing in this round.
The ₹37,102 price values Ecopmin at about ₹895 crore before the money comes in and ₹1,000 crore after. That figure comes from a simple formula: management projects a profit after tax (PAT) of ₹100 crore for October 2026 to September 2027, and investors apply a 10x multiple to it.
Investors will hold about 10.5% of the company after conversion.
The notice also cites a registered valuer, ValuGenius Advisors LLP. In its 13 November 2026 report it put fair value at ₹20,728 per share. The investors are paying about 1.8 times that, which shows how much they are relying on the company hitting its profit projection.
The CCPS do not convert at a fixed price. Once the audited accounts for October 2026 to September 2027 are final, the price resets to actual PAT × 10, capped at a ₹1,000 crore post-money valuation. The notice illustrates three cases:
Scenario | Actual PAT (₹ cr) | Post-money valuation (₹ cr) | Price per share (₹) | Investors' shares | Investors' stake |
|---|---|---|---|---|---|
| Base case | 100 | 1,000 | 37,102 | 28,300 | 10.50% |
| Profit falls short | 95 | 950 | 35,029 | 29,975 | 11.05% |
| Profit beats target | 110 | 1,000 (capped) | 37,102 | 28,300 | 10.50% |
This works one way. If Ecopmin misses its target, investors get more shares and existing shareholders are diluted more. If it beats the target, the cap means existing shareholders get no benefit.
The profit figure is strictly defined. It excludes one-off gains, subsidies, scrap sales, ESOP costs and unrealised forex gains. A Big 4 firm calculates it, and PwC or an affiliated firm carries out financial due diligence.
The notice names three uses for the funds:
Working capital
Capital expenditure
Repaying loans from promoters and related parties
The investors get more than shares. Under the Shareholders' Agreement dated 6 November 2026, they get voting rights on an as-converted basis and affirmative (veto) rights on reserved matters. They also get a liquidation preference. No dividend can be paid to equity holders without their written consent. The company is adopting new Articles of Association to reflect these terms.
The notice says control does not change. Managing Director Perumal Vinoth holds 48.77% today. In the base case, his stake falls to about 43.6% after conversion (our calculation from the notice's share counts).
Before bringing in investors, Ecopmin is tidying its cap table. In August 2020 it issued 10,000 zero-coupon convertible debentures worth ₹1 lakh to five employees. Under the original terms these would convert into 10,000 equity shares, about 4% of today's equity.
Under the amended terms they will convert into just 10 shares, at ₹10,000 per share. All five holders have agreed in writing. The change protects existing shareholders from that dilution and makes the fully diluted share count clear for the new investors.
The round puts a well-known institutional investor behind Ecopmin at a ₹1,000 crore valuation. That is a strong signal for an unlisted company with a large base of retail shareholders. The valuation, though, rests on one number: ₹100 crore of PAT in the year to September 2027.
Shareholders should watch three things:
The profit target. Every shortfall in PAT means more dilution for existing holders.
Promoter loan repayment. Part of the new money may go to promoters and related parties rather than into the business.
Investor rights. Veto and dividend-consent rights give the new investors a large say in future decisions.
Source: Ecopmin Technologies Private Limited, Notice of Extraordinary General Meeting dated 16 November 2026. This article is for information only and is not investment advice.