
1. The business in brief
Adiance designs and manufactures surveillance cameras, recorders and video software, mostly for other companies to sell under their own brand (OEM, ODM and joint design). Its own brands are Adiance and ArcisAI. Beyond the camera, it supplies the full stack a partner needs to launch a surveillance product:
The company serves government (B2G), enterprise (B2B) and consumer (B2C and D2C) customers, and also offers contract PCB assembly. Promoters hold 90.3%.
Key numbers (₹ crore)
| Metric | FY23 | FY24 | FY25 | What it shows |
|---|---|---|---|---|
| Revenue | 19.2 | 52.8 | 131.2 | ~2.6× a year for two years |
| Operating profit (EBITDA) | 2.4 | 7.1 | 29.8 | Grew faster than revenue |
| EBITDA margin | 12.7% | 13.4% | 22.8% | Jumped in FY25 — check mix |
| Profit before tax | 1.1 | 5.0 | 23.8 | |
| Profit after tax | 0.5 | 3.2 | 17.5 | 13.3% net margin in FY25 |
| EPS (₹) | 24.2 | 23.1 | 125.9 | FY24 EPS flat as share count rose |
| Net worth (FY25) | ~44.2 | Book value ₹316.6 per share | ||
| Debt / equity (FY25) | 0.25 | Borrowings ~₹11 cr; lightly geared | ||
2. The product range
Everything below is sold under the ArcisAI brand or white-labelled for partners. All cameras run on non-Chinese chips.

S-Series edge-AI cameras
AI runs on the camera itself: face, intrusion, ANPR and people counting without a server.
- Types
- Bullet, dome, PTZ (3MP; 5G PTZ)
- Connectivity
- 4G, Wi-Fi, PoE

Eco-Series security cameras
Budget range for multi-site rollouts such as banks, schools and retail chains.
- Types
- Dome, bullet, PTZ (3/5MP), Wi-Fi baby PTZ
- Connectivity
- 4G, Wi-Fi, PoE
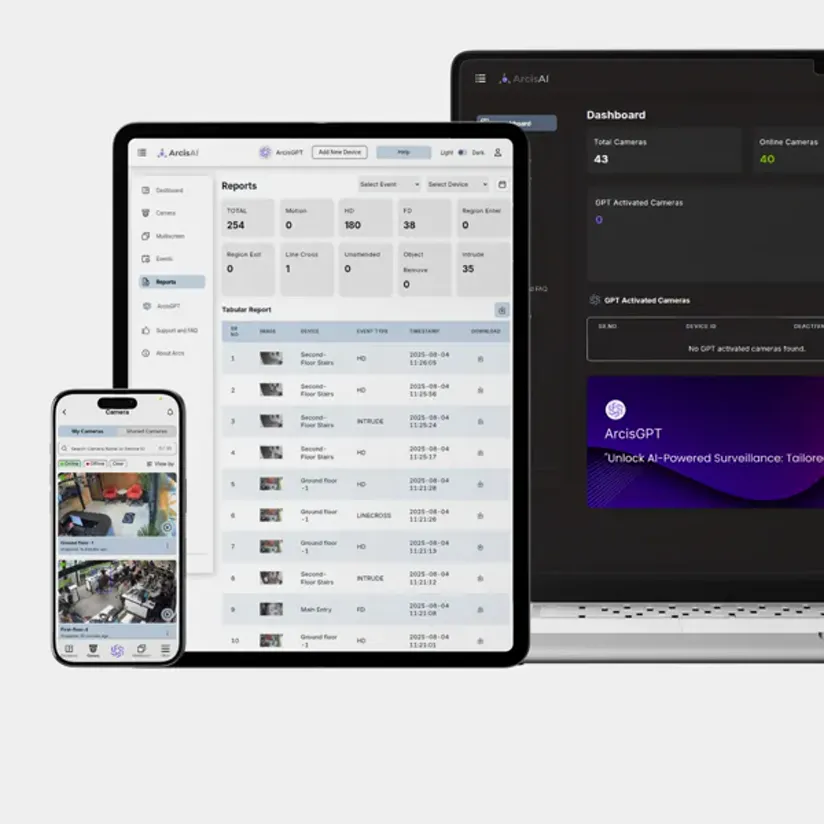
ArcisAI cloud VMS
STQC-certified video management platform, resold under the partner’s brand and domain, with a branded iOS/Android app.
- Functions
- Live view, playback, AI alerts, health dashboard
- Compliance
- STQC, ONVIF

Arcis Bridge Device (ABD)
Plug-in box that connects any ONVIF camera, including other brands’, to the ArcisAI cloud — turning installed cameras into monthly software income.
- Works with
- ONVIF cameras of any brand

ArcisAI NVRs
On-premise recorders for sites that need local storage.
- Models
- 4-channel (2 TB), 16-channel (4 TB)

OEM / ODM manufacturing
35+ models built to a partner’s spec: 4K, thermal, ANPR, 4G/5G, edge-AI. Also PCB assembly, and a robotic-arm line for industrial automation.
- MOQ
- 100 units
- Lead time
- 8–12 weeks to branded production
Product images: adiance.com.
3. How Adiance makes cameras
The key design choice is the chip. Most low-cost CCTV cameras worldwide run on Chinese system-on-chips. Adiance builds on Qualcomm, Ambarella, Novatek and Sigmastar chips instead, which makes its products compliant with the US NDAA Section 889 ban on Chinese-origin surveillance components and with India’s tightening security-testing rules.
- Engineering in-house. PCB design, firmware, enclosure, lens calibration and AI-model tuning are done internally. Number-plate recognition is trained for US, EU, GCC and Indian plate formats.
- Manufactured in India. Over 35 models across dome, bullet, PTZ, 4K, thermal, ANPR, 4G/5G and edge-AI.
- Small orders, fast turnaround. Minimum order from 100 units; a partner’s branded product can be in production in 8–12 weeks.
- Certified for tenders. BIS registration R-72003735 (covering Adiance and ArcisAI), STQC certification for the cloud VMS, plus FCC, CE, RoHS, ONVIF and ISO.
4. Who it supplies to
- Export white-label. Distributors, system integrators, telecom operators and brands in the US, UK, EU, GCC and Australia/New Zealand, where supply-chain rules increasingly decide who can bid for tenders. Adiance has a US sales office.
- Indian projects. Smart and safe city, traffic management, banks and ATMs, schools and exam halls, hospitals, retail, transport and construction.
- Sister company VMukti Solutions Verify. VMukti is an Ahmedabad video-management and command-centre integrator, founded in 2007 by the same Sanghvi promoter family. It reports election webcasting across 1.42 lakh+ cameras at 65,000+ polling booths and about 3.5 lakh cameras supplied in total, making it a likely large buyer of Adiance hardware.
What this means: FY25 (April 2024 to March 2025) covered the Lok Sabha elections, the same year revenue jumped 148%. If election webcasting through VMukti drove much of that, FY25 revenue may be lumpy and related-party heavy. The related-party note in the FY25 annual report should be checked before treating FY25 profit as a base.
5. What protects the business
The protection is real but narrow. It comes mostly from regulation, not from brand or scale.
Working for Adiance
- Rules favour non-Chinese chips in both India (STQC testing) and the US (NDAA). Few Indian makers qualify.
- Full stack under the partner’s brand is harder to copy than a camera and keeps customers longer.
- 100-unit minimum order serves smaller brands that large manufacturers ignore.
- 22.8% EBITDA margin vs 13.7% at CP PLUS suggests pricing power in its niche.
Limits
- Small: about 3% of CP PLUS’s revenue, with no consumer brand.
- Switchable: white-label customers can move to another manufacturer.
- Chips open to all: CP PLUS has its own Qualcomm edge-AI partnership.
- Concentration: likely reliance on a related party; limited disclosure.
6. Adiance vs Aditya Infotech (CP PLUS)
Aditya Infotech, listed in July 2025, sells India’s largest CCTV brand, CP PLUS. Management puts its market share above 45%. It began as a distributor and is now building its own manufacturing at Kadapa, Andhra Pradesh: 25 lakh units a month today, to double in two years, with a new enclosure plant due by Q3 FY27.
| Metric | Adiance | Aditya Infotech (CP PLUS) |
|---|---|---|
| Model | White-label manufacturer + cloud stack | Own brand + national distribution, backward-integrating |
| Revenue (latest FY) | ₹131 cr (FY25) | ₹4,221 cr (FY26) |
| Revenue growth | +148% | +36% (FY26) · +90% (Q1 FY27) |
| EBITDA margin | 22.8% | 13.7% (guided 14–15% for FY27) |
| Profit after tax | ₹17.5 cr | ₹368 cr (FY26) · ₹142 cr (Q1 FY27) |
| Main markets | Exports (US, EU, GCC) + Indian projects | India: government, enterprise, retail |
| Chips | Non-Chinese (Qualcomm, Ambarella, Novatek, Sigmastar) | STQC-compliant range; Qualcomm tie-up |
| Watch-out | FY26 numbers not yet public | FY26 operating cash flow ~4% of PAT |
7. Valuation at ₹3,400 per share
Adiance has 13,95,950 equity shares of ₹10 face value.
| Metric | Value | How it is calculated |
|---|---|---|
| Market capitalisation | ₹474.6 cr | 13,95,950 shares × ₹3,400 |
| Enterprise value | ~₹485.6 cr | Market cap + debt ~₹11.0 cr (0.25 × net worth); cash not disclosed |
| EV / EBITDA (FY25) | 16.3× | ₹485.6 cr ÷ ₹29.8 cr |
| EV / Revenue (FY25) | 3.7× | ₹485.6 cr ÷ ₹131.2 cr |
| Price / Book | 10.7× | ₹474.6 cr ÷ net worth ₹44.2 cr |
| P/E (FY25) | 27.1× | ₹474.6 cr ÷ PAT ₹17.5 cr |
Against CP PLUS
| Multiple | Adiance | CP PLUS | CP PLUS basis |
|---|---|---|---|
| P/E | 27× | 91× | ₹43,300 cr ÷ TTM PAT ~₹477 cr (118× on FY26) |
| P/E on next-year earnings | — | 70–85× | FY27 guidance: ₹6,000–6,500 cr × 8.5–9.5% margin |
| EV / EBITDA | 16× | ~75× | FY26 EBITDA ₹579 cr; near net cash |
| Market cap / Revenue | 3.6× | 8.9× | TTM revenue ~₹4,883 cr |
| Price / Book | 10.7× | ~12.5× | Reported, Sep-2026 |
At CP PLUS’s trailing multiple, Adiance’s FY25 profit alone would be worth about ₹1,600 crore, more than three times today’s ₹475 crore. The discount pays for illiquidity, a 6-month lock-in after any IPO, roughly 30× smaller scale, thinner disclosure and the risk that FY25 was an election-year peak.
The deciding number is FY26 revenue. If Adiance held or grew revenue in a year without a national election, 27× looks undemanding. If revenue fell back, 27× is being paid on peak earnings.
IPO timing: no draft offer document has been filed.
8. Points to keep in mind
- FY26 results. Not yet public. The valuation above uses FY25, which is now 18 months old.
- Related-party sales. The share of revenue from VMukti and other Sanghvi-family entities, and the pricing terms, should be confirmed from the annual report.
- Election linkage. Election webcasting peaks around national and state polls; revenue may swing between years.
- Export progress. The NDAA story depends on actual US and Europe orders; the export share of revenue is not yet disclosed.
- Cash conversion. Operating cash flow, receivable days and inventory should be checked against reported profit.
- Price movement. The indicative price has risen 51% in six months; trading in the share is thin.